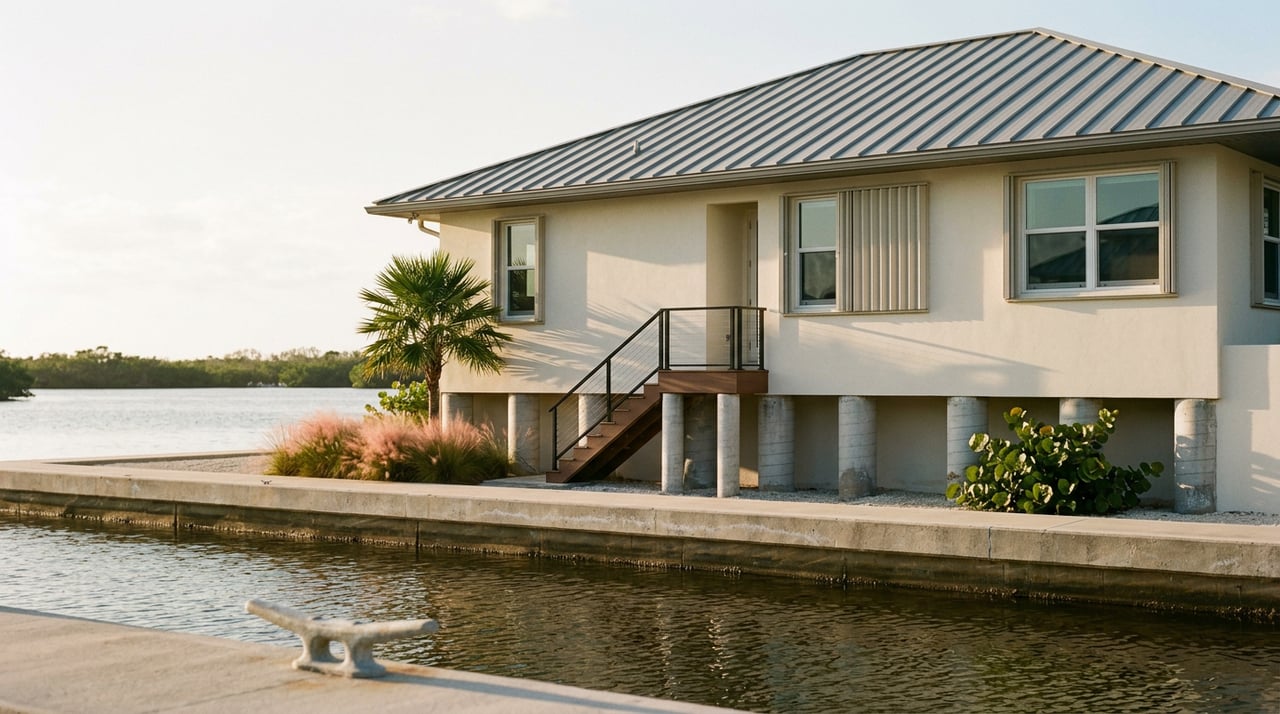
Islamorada's Wind Mitigation Form Changed in April. Most Listing Files Still Don't Know It.
September 24, 2026
September 24, 2026
There is a document sitting in most Islamorada listing files that nobody reads until an insurance quote comes back wrong. It is the wind mitigation report, the form that tells a carrier whether a roof, a set of windows, or a garage door earns a discount for standing up to hurricane wind. For years it was a formality: get it done once, keep it in the file, hand it to the next buyer's agent. As of this year, that assumption is the thing most likely to slow a Keys closing down.
The state rewrote the form itself on April 1, 2026, and insurers started pricing against the new version in July. A report that was perfectly valid in March may now be technically acceptable but functionally thin, missing the documentation a carrier wants before it will apply the full credit. In a market where the carrier pool writing Keys wind coverage is already narrow, that gap does not just cost money. It costs time, at the exact moment a buyer's financing clock is running.
A wind mitigation inspection checks six things: roof covering, roof deck attachment, roof-to-wall connection, roof shape, opening protection, and secondary water resistance. A licensed inspector, contractor, or engineer documents what they find on a form recognized statewide, and the insurer uses that form to apply premium credits under Florida Statute 627.0629, which requires carriers to offer them when the features are verified.
The report itself is valid for up to five years, as long as nothing material changes on the structure. That five-year window is the quiet mechanism at work here. A lot of Islamorada homes carry a report from 2022 or 2023 that is still inside its valid window on paper, but was written to a documentation standard the state has since replaced.
The Florida Office of Insurance Regulation updated the Uniform Mitigation Verification Inspection Form, OIR-B1-1802, effective April 1, 2026, the first major revision in over a decade. The update followed a 2024 wind-loss mitigation study that reexamined how much each construction feature actually reduces storm damage. The practical difference for anyone selling or buying right now is documentation. The new form asks for more proof behind each claimed feature: photos, product approval numbers, permit records tied to the work.
| Older reports (pre-April 2026) | Reports under the revised form | |
|---|---|---|
| Feature verification | Inspector checkbox, minimal backup | Photos and product approval numbers expected |
| Permit trail | Rarely requested | Often requested to support the claim |
| Insurer review | Generally accepted as filed | May trigger follow-up requests for missing proof |
| Valid for | Up to 5 years from inspection date | Up to 5 years from inspection date |
Insurers were told to begin applying credits based on the new form starting in July 2026. That created a short window where an older report and a newer one can sit side by side, both technically valid, producing different quotes. A report is not automatically wrong because it predates April. It may simply lack the backup a carrier now wants before honoring the full discount, which is a different problem with the same result: a delayed or lower quote landing on a buyer's desk mid-transaction.
Islamorada spans six islands between Key Largo and Marathon, and every one of them sits fully exposed to Atlantic wind and Florida Bay surge with no buffer of inland acreage behind it. That geography shows up directly in the insurance market. Independent agencies writing policies here describe needing to shop well over a hundred carriers to find competitive coverage, because so few companies are willing to write Keys wind risk at all. A 600,000 dollar dwelling in the Keys commonly runs 6,000 to 12,000 dollars a year for basic coverage in 2026, with waterfront and elevated homes landing at the higher end given their wind and surge exposure. Broader estimates for Islamorada homeowners coverage in 2026 put the range closer to 1,800 to 3,500 dollars a year, with the spread driven heavily by whether a wind mitigation report is on file and how complete it is.
In a market with a deep bench of carriers, an incomplete report just means slightly higher premium. In a market where a handful of carriers are actually writing policies, an incomplete report can mean a longer underwriting queue while the carrier requests the missing documentation, or a quote that comes back at a number that changes a buyer's calculation on the property entirely.
The instinct is to treat a wind mitigation report like a home inspection: do it once, file it away, move on. But the report is really an insurance underwriting document with a shelf life, and the shelf life question that matters right now is not "has it expired" but "was it written before or after April 1." A report from three years ago is still valid by the calendar. Whether it holds up under the current documentation standard is a separate question, and it is the one that determines how smoothly the buyer's insurance quote comes together.
Sellers who ordered a new roof, impact windows, or storm shutters any time in the last few years and never updated the report are also leaving discounts unclaimed, discounts that a buyer's insurance shopping will surface anyway. Better to surface them before listing, when there is time to act on them, than after an offer is already in.
For anyone listing or under contract on an Islamorada home right now, the order of operations matters more than it did a year ago.
None of this changes what the home is worth. It changes how quickly a transaction moves once it is in motion, which in the Keys' tight carrier market is often the more urgent variable.
The homes that close without friction this year tend to have one thing in common: the wind mitigation report was current, complete, and in the listing packet before the first showing. The homes that stall are the ones where a buyer's insurance agent calls three weeks into the contract asking for photos the original inspector never took, or a permit number nobody can locate for a roof replaced years ago. The Village of Islamorada Building Department, at 86800 Overseas Highway, keeps permit records that can fill some of those gaps, but chasing that paperwork after an offer is accepted is slower than pulling it before the sign goes in the yard.
None of this is a reason to be alarmed about owning waterfront property here. It is a reason to treat one specific form as part of the listing preparation rather than an afterthought, the same way a seller would confirm survey documents or a certificate of occupancy before going to market.
Does every Islamorada home need a new wind mitigation inspection this year? No. If the current report was written after April 1, 2026, and includes the documentation carriers are now asking for, it should carry forward without issue. The reports that need attention are the ones written before that date on homes that have had upgrades since.
Who can perform the inspection? A Florida-licensed home inspector, building code inspector, general or residential contractor, professional engineer, or architect can complete the form, as long as they hold the required credentials under state law.
Does a strong wind mitigation report guarantee a lower premium? No. It documents features that qualify a home for credits, but each carrier applies its own underwriting rules to the report. A complete report gives a buyer's agent the best chance at the discount, not a fixed number.
If you are weighing when to list an Islamorada waterfront home, or trying to make sense of an insurance quote that came back higher than expected on a home you are under contract for, Sally Stribling has spent decades working through exactly this kind of Keys-specific detail with buyers and sellers. Let's Connect before the paperwork becomes the bottleneck instead of the proof of value it is meant to be.
Stay up to date on the latest real estate trends.
We pride ourselves in providing personalized solutions that bring our clients closer to their dream properties and enhance their long-term wealth. Contact us today to find out how we can be of assistance to you!